Unexpected Business Expenses That Can Disrupt Your Cash Flow
48% of small businesses buy goods or materials from abroad, according to the Federal Reserve’s 2026 report.
Most of them said prices have increased compared to the previous year.
Rising prices are only one of the costs that can put your company at risk.
Knowing the most common unexpected business expenses and how to prepare for the gap they create helps you keep paying staff and suppliers while your business continues running smoothly.
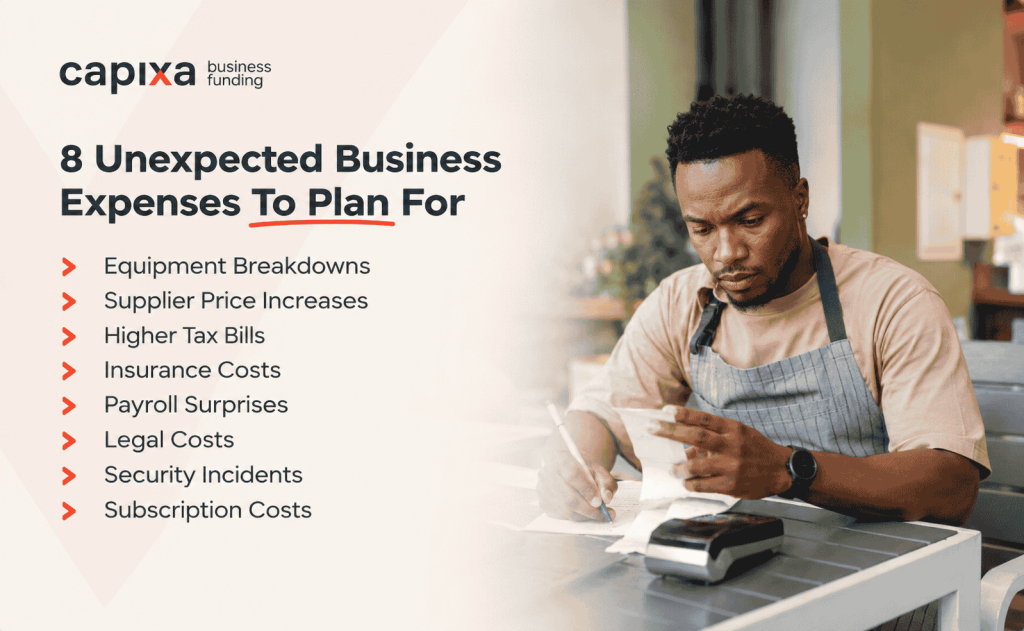
8 Unexpected Business Expenses That Can Catch Owners Off Guard
Some small business expenses can happen unexpectedly. Others are regular costs that you’ve forgotten or that suddenly increased.
1. Equipment Breakdowns and Emergency Repairs
No matter whether you work in a restaurant, run a construction company, a medical practice, or a retail store, the equipment you use can fail.
Ovens, delivery vehicles, HVAC systems, medical devices, and point-of-sale hardware can all break down without warning.
In these situations, the repair bill may not be the only cost you have to worry about. Until you replace what’s broken, you may lose hours of operation, lose sales, need to rent replacement equipment, or pay employees overtime to get back on track.
2. Supplier Price Increases
Even if you don’t import anything yourself, your suppliers may, and tariffs on their goods can push your costs up too.
When a supplier raises prices without warning, each sale costs you more right away.
Passing that cost on to customers isn’t always simple.
Say you run a boutique and restock winter coats in October. Your supplier raises wholesale prices by 15%.
You could raise your prices, too, but you’ve already advertised a holiday sale, and a sudden price jump in the middle of the season could send shoppers to a competitor.
So, you absorb the extra cost on every coat until the season ends.
3. Higher Tax Bills
A successful year for sales can also mean a bigger tax bill than you planned for.
Some businesses, such as sole proprietorships, partnerships, and S corporations, pay estimated taxes four times a year, based on what they expect to owe.
If you planned for less income than you earned, you’ll owe the difference when you file your tax return.
4. Insurance Premiums and Deductibles
Your premium can jump at renewal after you file a claim or when insurers raise rates across your industry or area.
Think of a situation when a burst pipe floods your store, and the repair costs $30,000.
With a $5,000 deductible, you pay the first $5,000 before your policy covers the rest, and your premium may go up at renewal because you filed a claim.
5. Payroll Expenses
Payroll can also bring surprises. It can be pushed above budget in various scenarios, such as
- Recruiting and training new hires
- Increase in the state minimum wage
- Taking extra staff during a busy season
- Overtime when orders pick up or a team member is out sick
- Replacing a key employee who leaves unexpectedly
- Paying out unused vacation time when someone leaves if required by the state
- Higher health insurance costs for your team at renewal
6. Legal, Compliance, and Licensing Costs
If a client refuses to pay for a finished job, you’ll need to pay an attorney to recover the money.
Missing a license renewal or failing a safety inspection can cost both a fine and expenses to fix the problem.
And if the authorities require more information about your tax filings, your accountant will likely work extra hours to compile the paperwork and respond.
7. Technology Failures and Security Incidents
If your online store or hotel booking system goes down, you can’t work until it’s back up and must likely pay a developer to fix it.
A hacked email account can cost even more, since you may need an IT specialist to secure your systems and time to contact customers whose information was exposed.
8. Rising Software and Subscription Costs
Every day, you use various systems, from accounting software to scheduling apps.
If their subscription prices rise or you’re using multiple software tools and platforms, you can end up with a noticeable monthly expense.
Why Unexpected Expenses Can Create Cash Flow Problems
When a surprise bill is due now, and the money to pay it is still weeks away in unpaid invoices or future sales, such a situation can leave you without enough funds for rent, payroll, or supplier payments, even if your business is profitable.
Here’s an example: A landscaping company provides a service and issues an invoice for $40,000 in September with 30-day payment terms.
Then a mower engine fails, and the replacement costs $6,500, which must be paid now. The money to cover it is on its way, but it isn’t in the bank yet.
This timing mismatch between when you have to pay and when you get paid is how unexpected expenses in business affect:
- Your cash reserve: The money you set aside for emergencies shrinks or disappears.
- Your regular bills: You still must pay rent, payroll, and supplier invoices.
- Your ability to take on new work: Cash spent on a repair doesn’t allow you to buy materials for the next job.
Read more about how to manage cash flow effectively.
How To Prepare for Unexpected Business Expenses
Although you cannot predict every surprise, you can take a few key steps to cover different scenarios.
Build a Cash Reserve
Keep funds in a separate account and use them only for emergencies.
Start by adding up money that can cover one month of your fixed monthly costs: rent, payroll, insurance, loan payments, and software subscriptions. Then build toward two or three months.
One of the ways to build a cash reserve is by moving a percentage of every deposit into that account. This works faster than waiting for leftover cash at the end of the month.
Forecast Cash Flow Week by Week
Plan the money coming in and going out over the coming weeks. A 13-week forecast (one quarter) is a practical length for most small businesses.
Update it weekly with real numbers, so you can see when a tight week is coming in advance.
Keeping proper bookkeeping will help your business run smoothly.
Plan for Equipment Replacement
List your key equipment, its age, and its expected lifespan. Schedule regular maintenance and set money aside each month for the item most likely to fail next.
Set Aside Tax Money as You Earn
Move a fixed percentage of each payment you receive into a separate tax account. Your accountant can help you decide on the right amount based on last year’s return.
Review Contracts and Insurance
Check supplier contracts for clauses mentioning price increases.
Confirm your insurance deductibles and make sure you’ve got the right coverage for your business type and size.
Check Out Funding Options Before You Need Them
Applying for funding when an emergency comes means making decisions under pressure.
Talk to a trusted funding partner to see what type of business funding can fit your business structure and needs.
- A business line of credit negotiated during a calm month provides you with access to a set amount you can draw from when needed, and you pay interest only on what you use.
- A small business loan secures a lump sum for a larger one-time cost, such as replacing a delivery van. You can repay it in fixed amounts over a set term.
- Revenue-based financing allows you to use funding and repay it in the form of a percentage of your sales. This lets you pay more in busy months and less in slow ones and is often chosen by seasonal businesses.
Turn to a Trusted Funding Partner in an Emergency
Even with a plan in place, some costs will still catch you off guard.
Having a funding partner who knows your business will help you address the challenge and avoid taking the first offer just because the bill is due.
Find Funding for Unplanned Business Expenses With Capixa
Capixa works with business owners across many industries to match funding to the situation they’re facing.
Through our network of banks, lenders, and brokers, we compare various options and recommend the one that best fits your needs, while helping you avoid common business funding mistakes.
With Capixa, you can get funding up to $1M and decisions in as little as 24 hours.